01
Refinance, not new borrowing.
We keep the refinance to your existing borrowing. The ATO hasn’t yet said when a refinance might be treated as a new arrangement, so we don’t increase the loan.
Still paying a high interest rate on your SMSF property loan?
Rates and lender policies have moved since most SMSF property loans were set up. Loans in place before the August 2026 changes can still be refinanced, and your fund keeps the property it already owns.
SMSF LOAN REVIEW · REFINANCE ONLY
With Vineet Danwar, Chartered Accountant & Mortgage Adviser
From 10 August 2026, an SMSF can no longer take out a new limited recourse loan to buy residential property.
Loans in place before then are grandfathered. The ATO has confirmed that refinancing them isn’t affected by the new rules.
With fewer new SMSF loans being written, some lenders have simplified how they assess SMSF refinances. Your loan may no longer be the best fit.
Based on information available as at November 2026. Rules and lender policies can change. This is general information, not financial product advice.
A refinance review is about more than the headline rate. We look at how the loan fits your fund as a whole.
Your fund’s contributions, rent, expenses and member balances all affect what a lender will offer and what you can comfortably repay. As a Chartered Accountant and mortgage adviser, Vineet reads the fund the way a lender does, and works alongside your SMSF accountant, auditor and licensed financial adviser.
We keep the refinance to your existing borrowing. The ATO hasn’t yet said when a refinance might be treated as a new arrangement, so we don’t increase the loan.
SMSF property loans use a holding (bare) trust. A refinance usually keeps it, with the new lender and your solicitor confirming any documents needed.
A lower rate only helps if repayments still suit your fund’s income and buffer. We check both before recommending a lender.
Discharge, application and legal fees all count. We set them against the saving so you can decide with the full picture.
“Banks will not issue loans against every trust structure, a detail I never knew and one that is often overlooked.”
“Vineet understands internal financial traits that could create significant issues later during the financing or acquisition stages. … The team is super proactive.”
“Most brokers arrange a loan. Vineet plans the structure behind it.”
“He positioned our portfolio properly and in the right order, and when the budget turned the market upside down, that groundwork is what protected us — we came through it secure, with our borrowing capacity largely preserved. … Genuinely strategic advice, not just finance.”
“Their understanding of finance, combined with their strong accounting knowledge, made a real difference.”
“Vineet and his team kept me well informed throughout the process, patiently answered all my questions, and went above and beyond to develop the right mortgage strategy and structure.”
Selected excerpts from genuine Google reviews. Individual client experiences are not guarantees of future outcomes.
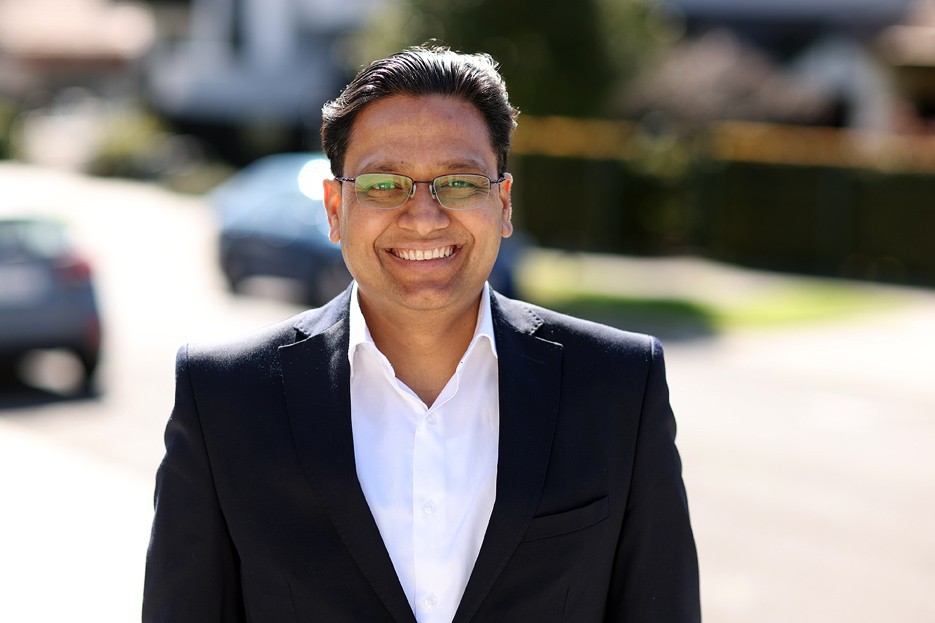
Chartered Accountant and mortgage adviser, founder of TransformBiz. Vineet spent more than 25 years in corporate finance and governance at PwC, Deloitte and Protiviti and in banking, before building a practice around one idea: structure comes before rate.
Finance by design, not by chance.
If the loan was in place before 10 August 2026, yes. Existing loans are grandfathered and the ATO has confirmed refinancing them isn’t affected. Lender approval and policy still apply.
We keep SMSF refinances to the existing borrowing. The ATO hasn’t issued specific guidance on when a refinance might count as new borrowing, so increasing the loan carries risk.
No. Refinancing replaces the loan, not the property. Your fund keeps the property it already owns.
We provide credit assistance and a Chartered Accountant’s view of the numbers. Decisions about your SMSF strategy should be made with a licensed financial adviser, and we’re happy to work with yours.
An initial conversation with no obligation. We look at your current loan and tell you whether a refinance looks worth exploring. Any fees are explained before you engage us.
Four quick steps, about two minutes. Tell us about your fund’s loan and we’ll take it from there.